Independent living appeals to many older adults: a private apartment, no home maintenance, and neighbors close by, without the daily care of assisted living. One of the first questions families ask is whether Medicaid pays for independent living, and the answer surprises many people.
This guide is for older adults and adult children who are planning a move to independent living, or comparing it with staying at home. It explains what Medicaid does and does not cover, which Vermont programs can help, and the most common ways people pay. Understanding this early helps avoid a move that is hard to sustain financially later.
The Short Answer: Medicaid Does Not Pay for Independent Living Itself
Medicaid does not pay for the housing costs of independent living. Rent or monthly fees, meals, utilities, and community amenities are considered room and board, and Medicaid does not cover room and board in senior housing. Medicare does not pay for independent living either.
The reason is how these programs are designed. Medicaid pays for medical care and long-term care services for people who meet financial and functional rules. Independent living is a housing choice for people who are largely self-sufficient, so there is usually no covered care service to pay for.
That does not mean Medicaid plays no role. If a person living independently starts to need help with daily activities, Medicaid may pay for some of those services, even though the housing cost remains the resident's responsibility.
What Independent Living Includes
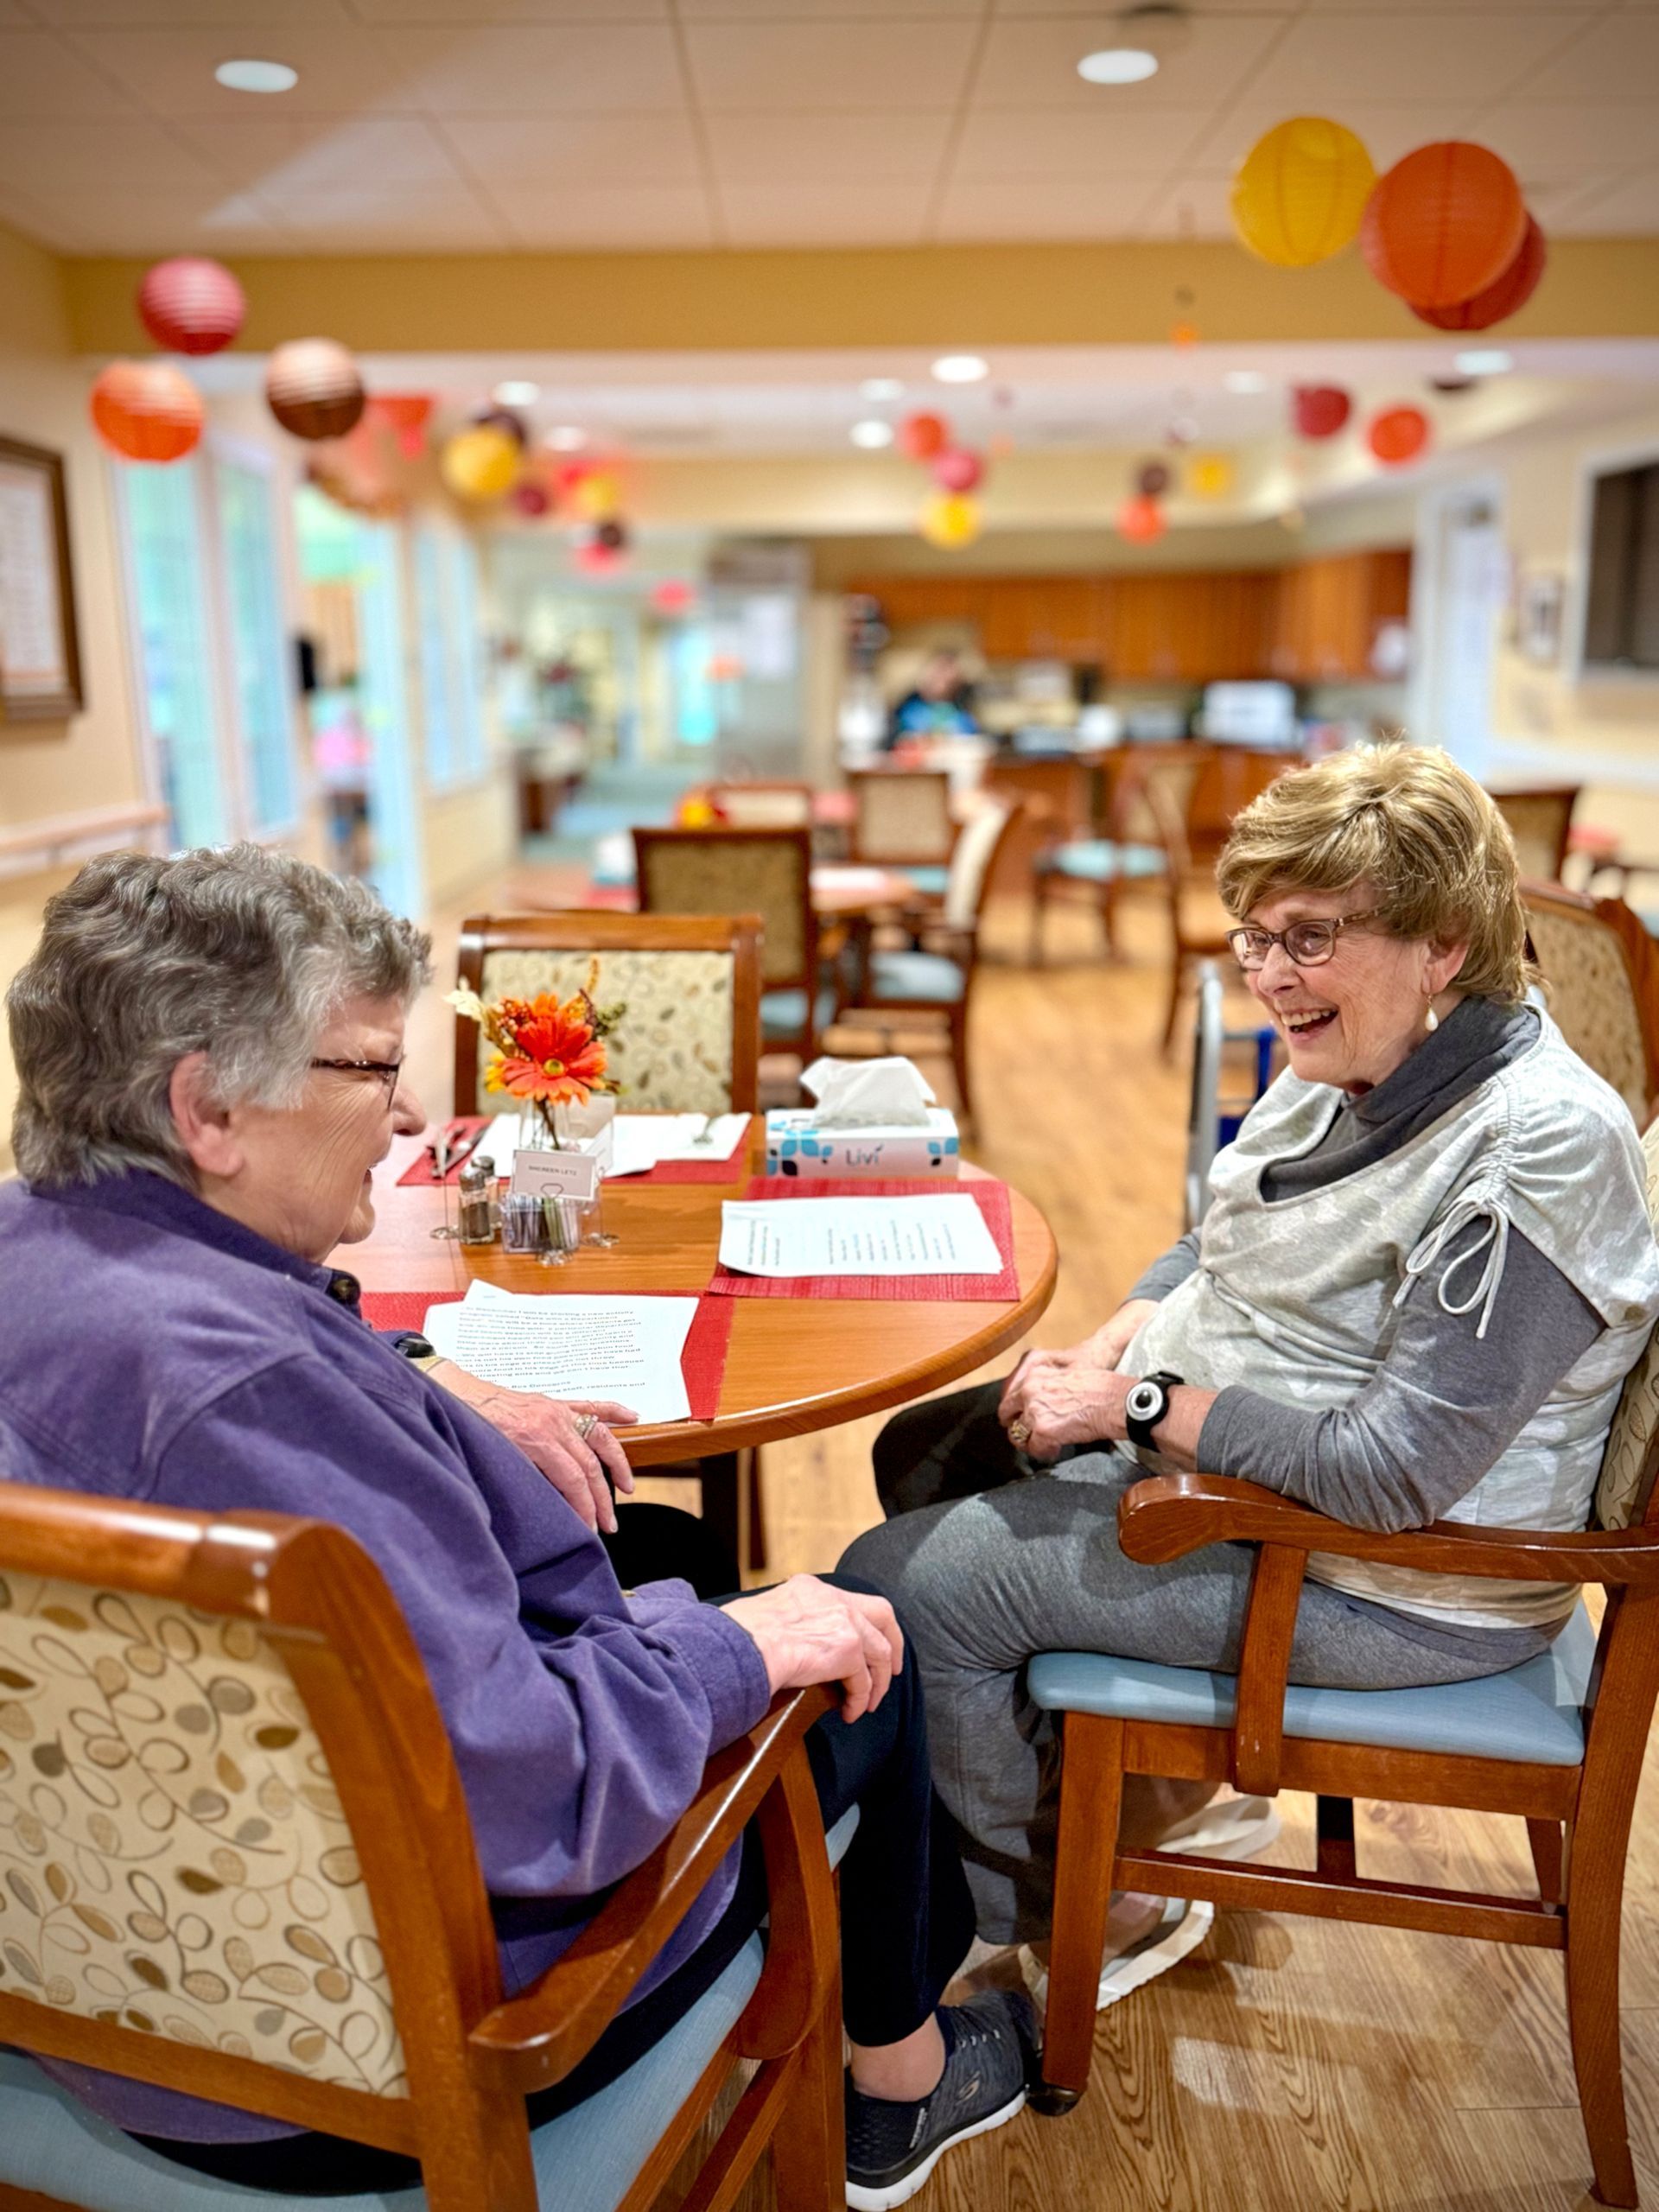
Independent living communities are designed for older adults who can manage their own daily lives but want convenience, safety, and social connection. Our guide to independent senior housing covers this in more detail. Typical features include:
- A private apartment or cottage
- Maintenance-free living, with exterior upkeep, snow removal, and repairs handled for you
- Some meals, housekeeping, or transportation, depending on the community
- Social activities and shared common spaces
Independent living generally does not include hands-on personal care, such as help with bathing, dressing, or medications. That level of support is provided in assisted living, which Vermont licenses separately.
When Medicaid Can Help: Care Services, Not Housing
Medicaid programs called Home and Community-Based Services (HCBS) help people receive care where they live rather than in a nursing home. Depending on the program and the person's needs, these services can include personal care, homemaker help, adult day programs, respite for family caregivers, and case management.
In Vermont, these services are offered through Choices for Care , the state's long-term care Medicaid program, which the Vermont Department of Disabilities, Aging and Independent Living (DAIL) oversees. It has two main paths.
Choices for Care: High and Highest Needs Groups
These groups are for people who meet nursing home level of care and Vermont Medicaid's financial rules. Eligible people can choose where to receive services, including at home with personal care and other supports, in approved assisted living settings, or in a nursing home. In each setting outside a nursing home, Medicaid pays for care services, while the person still pays for housing and food.
Choices for Care: Moderate Needs Group
The Moderate Needs Group is for people who need some help but do not meet nursing home level of care. According to DAIL, people in this group do not need to be eligible for Medicaid, but funding is limited. Services can include:
- Homemaker services, such as cleaning, laundry, and shopping
- Adult day services
- Case management
- A flexible fund for other approved supports
Because funding is limited, there may be a waiting list. Financial limits apply, so ask your local Area Agency on Aging for current figures.
Whether services from either group can be delivered in a particular independent living apartment depends on the community and the care plan. Ask both the community and the case manager before assuming services can follow a move.
Other Ways Older Adults Pay for Independent Living
Most people pay for independent living with a mix of personal resources and, in some cases, housing assistance.
Personal Income and Savings
The most common sources are Social Security, pensions, retirement accounts, and savings. Many people also use the proceeds from selling a home. Because independent living often replaces costs such as property taxes, home repairs, and utilities, it helps to compare the full cost of staying at home with the monthly fee of a community.
Long-Term Care Insurance
Long-term care insurance typically pays for care services, not housing. A policy will usually not cover independent living on its own, but it may pay for in-home care if a person living independently later needs help with daily activities. Review the policy's benefit triggers and elimination period.
Veterans Benefits
Eligible veterans and surviving spouses may qualify for a VA pension, which adds to monthly income. The Aid and Attendance supplement is tied to needing help with daily activities, so it more often applies once care needs increase. A county veterans service officer can help determine eligibility.
Affordable Senior Housing Programs
For older adults with limited income, federal housing programs can make independent living more affordable:
- HUD Section 202 senior housing: generally for people 62 and older with income below 50 percent of the area median income. Residents pay rent equal to 30 percent of their adjusted income.
- Housing Choice Vouchers: help eligible households pay rent in qualifying private housing. Waiting lists are common.
Vermont also offers SASH (Support and Services at Home) , which began in Vermont in 2011. SASH pairs residents of many affordable housing sites, and some community members, with a care coordinator and wellness nurse who help with health planning, medications, and connections to services. Participation is free.
Planning Ahead for Changing Needs
The most important financial question is not only how to pay for independent living today, but what happens if more care is needed later. A few steps can help:
- Ask whether the community offers assisted living, memory care, or skilled nursing nearby, and how residents move between levels of care.
- Estimate how long savings will last at current and higher costs.
- Learn Medicaid's financial rules early, including Vermont's 60-month look-back for long-term care Medicaid, so decisions about gifts or asset transfers do not cause problems later.
- Consider meeting with an attorney who focuses on Medicaid planning or a long-term care planner.
If assisted living may be the next step, our guide to whether Medicaid will pay for assisted living explains how coverage changes at that level of care.
Frequently Asked Questions
Does Medicaid pay for independent living?
No. Medicaid does not pay for rent, monthly fees, or meals in independent living, because these are considered room and board. Medicaid may pay for care services, such as personal care or homemaker help, for people who qualify for its long-term care programs.
Does Medicare pay for independent living?
No. Medicare does not cover independent living or other senior housing costs. It may cover certain medical services a resident receives, such as doctor visits or short-term home health care when specific conditions are met.
Can I get Medicaid help with care while living in an independent living apartment?
Possibly. Medicaid home and community-based services, such as Vermont’s Choices for Care, can pay for care services where a person lives. Whether these services can be delivered in a particular community depends on the program, the care plan, and the community’s policies, so ask both before moving.
What is the cheapest way to pay for independent living?
For people with limited income, HUD Section 202 housing generally sets rent at 30 percent of adjusted income for adults 62 and older with very low incomes. Housing Choice Vouchers can also help. Waiting lists are common, so it helps to apply early.
Does long-term care insurance cover independent living?
Usually not on its own. Long-term care insurance pays for care services once a policyholder meets the benefit triggers, such as needing help with daily activities. It may then cover in-home care for someone living in independent living, but not the housing cost.
Making an Informed Choice
So, does Medicaid pay for independent living? Not for the housing itself. Medicaid may help pay for care services once a person needs them, and in Vermont, Choices for Care offers support at different levels of need. Most people cover independent living with income, savings, and home equity, sometimes with help from VA benefits or senior housing programs. Planning for future care needs from the start makes it easier to choose a setting that remains affordable over time.
Cedar Hill Continuing Care Community in Windsor, Vermont, offers independent living, assisted living, memory care, and skilled nursing on one campus. Families who want to learn more can visit cedarhillccc.com.